Chapter 7 - The trust Dad created after Mom died
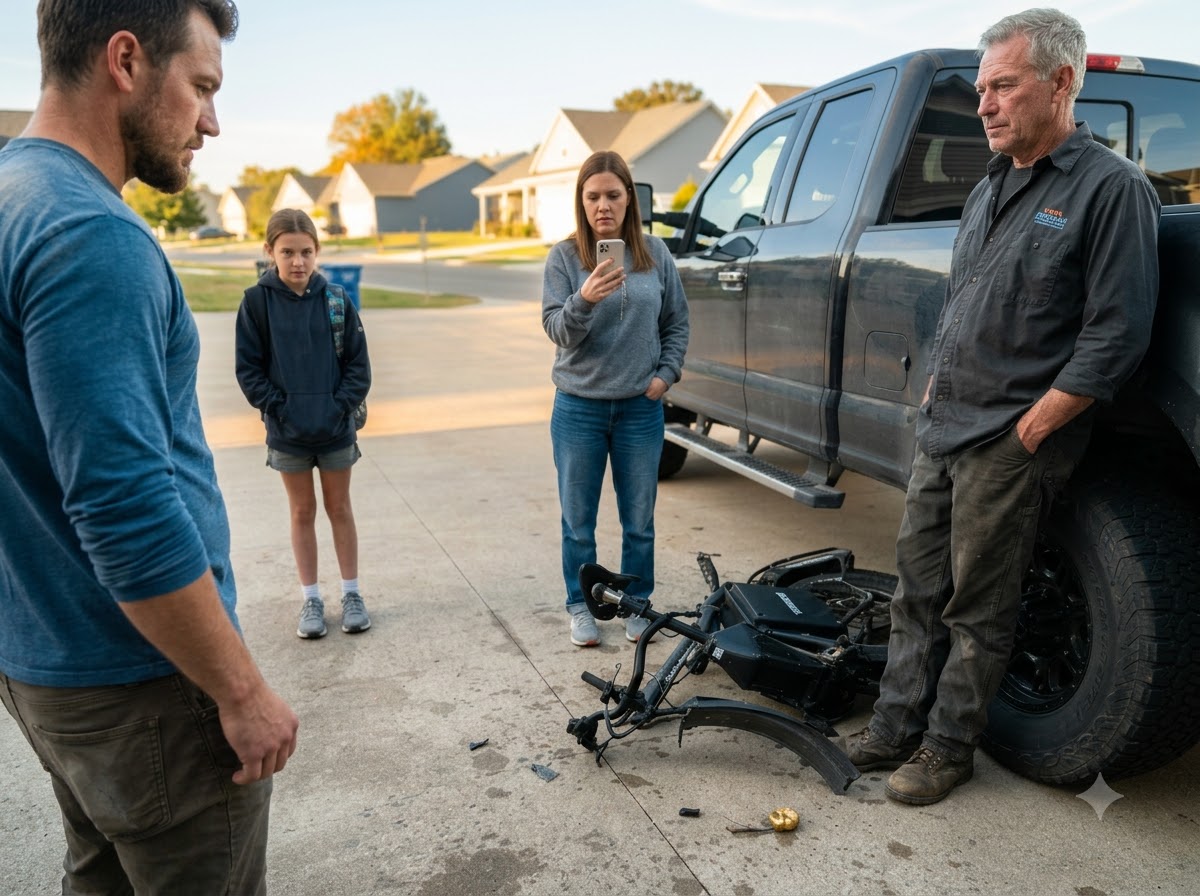
The Ryland Family Trust was not a fortune.
That disappointed nobody more than Noel, apparently.
Dad created it after Mom died six years earlier.
Assets:
His house.
A small brokerage account.
Part of his retirement rollover.
One life insurance policy.
Purpose:
Avoid probate.
Provide limited support for Noel and me.
Create education funds for grandchildren if enough remained.
Normal estate planning.
Why had he never told me?
“Didn’t think you cared.”
That was Dad’s defense for most information that contradicted his version of our family.
The trust named him trustee.
Successor co-trustees:
Me and Noel.
After his death.
Not now.
Neither of us had authority to pledge trust property while Dad lived.
Yet a lien appeared against the duplex in favor of Ryland Family Trust.
That lien itself was not harmful to the trust.
It meant the trust had supposedly loaned Noel’s LLC $45,000 secured by the duplex.
Did Dad actually lend $45,000?
Only $28,000 transfer existed.
Where did $45,000 come from?
Paper.
The promissory note stated the trust provided:
$28,000 cash plus $17,000 equipment contribution.
Equipment:
My generator.
Again.
They counted my equipment as Dad’s trust contribution.
Dad stared.
“I didn’t know about the seventeen.”
Noel had expanded the transaction after he signed.
His original promissory note draft left the equipment line blank.
Final version inserted it.
His signature was genuine.
The document had been altered after signing.
Different fraud than simple forgery.
Then Dana found an email.
Noel to Dad:
Need to show stronger equity for lender. I’ll add equipment value.
Dad:
Fine as long as Beck gets credit later.
He knew something would be added.
Not what.
Again, deliberate vagueness.
“What does ‘Beck gets credit later’ mean?” I asked.
Dad rubbed his forehead.
“I thought if we ever sold the duplex, we could pay you something for the equipment.”
“Something I never contributed.”
“I know.”
“You understand how insane that sounds?”
“Yes.”
Finally.
Then we reviewed the trust itself.
Mom had died with a $120,000 life insurance policy.
Dad put most into the brokerage account.
Over six years, he made several distributions.
$8,000 to help me replace a roof after storm damage.
I remembered.
$14,000 toward Noel’s divorce attorney.
$9,500 for Noel’s car.
$6,000 for Trey’s expenses.
Another $12,000 marked:
NR business support.
Noel again.
I had never known the trust funded those.
Dad had always said:
“I helped your sister.”
As if the money came only from him.
Some came from Mom’s insurance.
Did that make it wrong?
Not necessarily.
Dad had discretion.
But family narrative mattered.
Noel saw every distribution as evidence Dad would rescue her.
I saw Dad as repeatedly sacrificing his own retirement.
Neither picture was fully true.
Then we found one withdrawal:
$18,000.
Memo:
Cora education allocation.
My pulse changed.
I never received it.
Dad looked confused.
“I set something aside for her.”
“Where?”
He thought.
Then:
“Noel helped me open the account.”
Of course.
We traced it.
An investment account titled:
Cora Ryland Education Custodial.
Opened four years earlier.
Initial deposit:
$18,000.
Current balance:
$3,400.
I felt sick.
“Where did the money go?”
Withdrawals over three years.
Some for “education.”
Some transferred to Ryland Family Outdoor Services.
Custodian on account:
Noel.
Why Noel?
Dad said he thought both of us were custodians.
Paperwork named only her.
Was that allowed?
Depending on account type and terms, custodian had fiduciary responsibilities.
What were the withdrawals for?
Noel produced receipts later.
$1,800 for a laptop.
Not Cora’s.
$2,200 summer enrichment.
Trey’s camp two years earlier.
$4,500 business loan.
$3,000 vehicle repair.
None for Cora.
That was the moment my restraint almost broke.
Bike was property.
My identity was mine.
But this money had been set aside from my mother’s death benefit for my daughter.
Noel had used it for herself and Trey.
Dad stared at the statements.
“No.”
“Yes.”
“She told me that account was doing fine.”
“Did you ever check?”
“No.”
Again.
He covered his face.
For the first time since this began, I watched my father understand that his habit of trusting Noel without verification had not merely endangered me.
It had harmed Cora too.
Then Noel called Dana.
She wanted to explain.
I refused a direct conversation.
Dana put it on conference speaker with counsel.
Noel’s explanation:
She believed the education account was “family money.”
Dad had repeatedly said grandchildren should benefit equally.
Cora already “had more.”
So Noel moved money toward Trey and business needs intending to repay it.
Same logic as Grant in the previous story? We must not refer. Continue.
Borrow.
Replace later.
Noel had repaid:
$2,000.
Not enough.
Then she said something that made Dad lift his head.
“You always said Beck didn’t need the trust.”
Dad whispered:
“I said he was fine.”
“That’s the same thing.”
No.
It wasn’t.
But Dad had built the ambiguity.
His favoritism toward need had taught Noel that my stability canceled my claim.
Then Dana asked the key question:
“Did Beck know the account existed?”
“No.”
“Did Cora?”
“No.”
“Did you have authority to use it for Trey?”
Noel went silent.
Then:
“I thought Grandpa wanted fairness.”
There it was.
Fairness used to overwrite ownership.
Then Dana found one final transaction.
Two days before Noel crushed the bike, she attempted to withdraw the remaining $3,400.
Bank stopped it because the account was flagged after a beneficiary-age review.
Reason for transfer:
May you like
Summer camp.
Cliffhanger: Noel had already drained most of an education account created for Cora—and two days before crushing the bike, she tried to take the last $3,400 for “summer camp.”
Related Stories