Chapter 3 - My house had been part of their financial plan before their marriage even ended
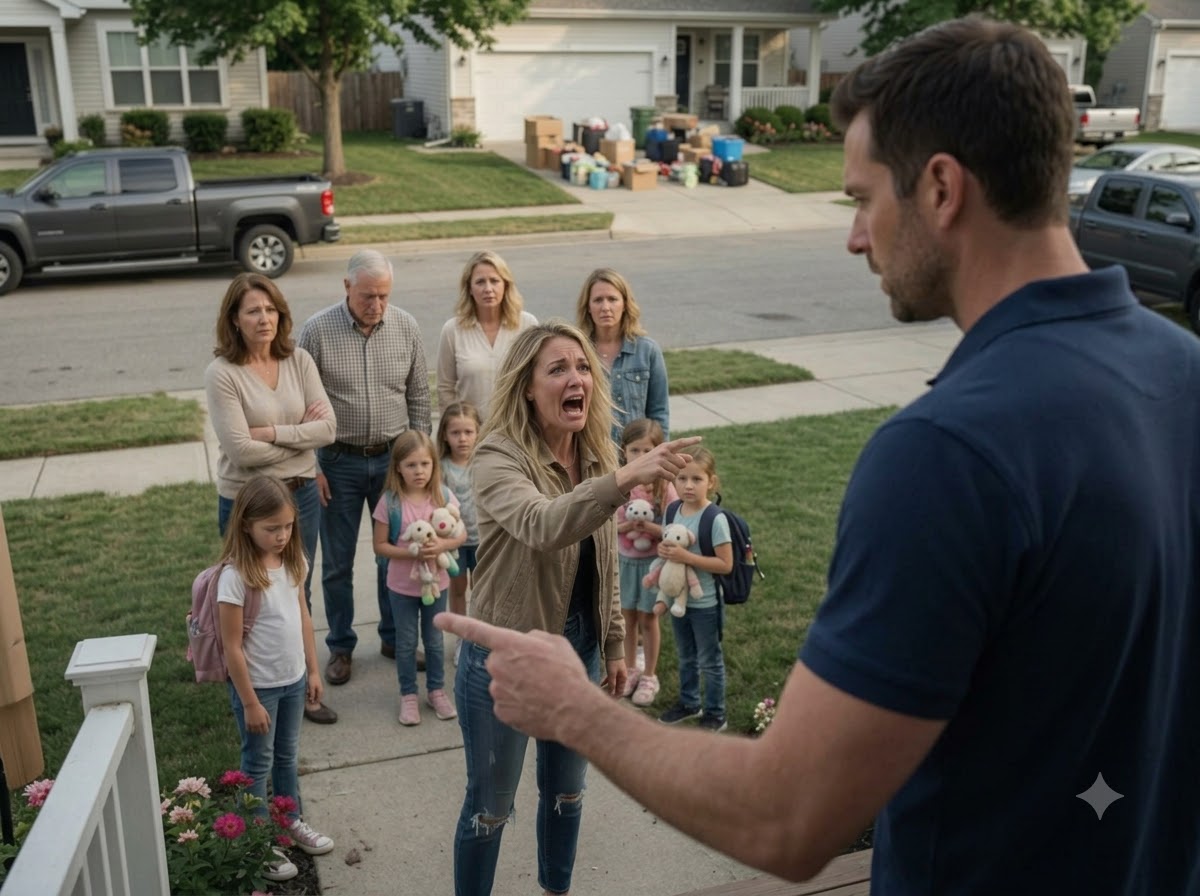
The more I learned, the less the front-lawn confrontation looked spontaneous.
Vanessa and Derek had been in financial trouble for nearly two years.
Not destitute.
Overextended.
Derek earned decent money selling commercial HVAC systems. Vanessa worked part-time in dental administration and had periodically left jobs when childcare became difficult.
Their problem was not one catastrophic event.
It was accumulated decisions.
Two financed SUVs.
Credit cards.
A boat they sold at a loss.
Private sports programs for the children.
A failed attempt by Derek to start a side business installing mini-split systems.
Then their landlord announced he would not renew the lease.
At that point, Derek proposed something.
Move into my house.
Why mine?
Because I traveled for work about eight to ten days a month.
Because I lived alone.
Because I had three bedrooms and a finished basement workshop that, in Derek’s imagination, could become a fourth sleeping space.
Vanessa told him:
“Ryan will say no.”
Derek responded:
“Your parents will make him.”
Those words appeared in texts Vanessa eventually produced.
My stomach went cold when I read them.
Not because they hated me.
Because they understood the family system accurately.
Derek knew Linda hated conflict.
He knew Richard compensated for guilt toward Vanessa after his divorce.
He knew I had historically surrendered rather than force everyone to choose sides.
So the plan was:
Ask.
Pressure.
Move in temporarily.
Stay long enough that removing them became morally difficult.
Then pay “some rent” once stable.
Was that illegal before they acted?
No.
Manipulative?
Yes.
Then Vanessa and Derek’s marriage deteriorated further.
He moved out.
But the house plan survived because both sides found different uses for it.
For Vanessa, my house became custody stability.
For Derek, it reduced the amount of temporary housing support Vanessa might request from him.
That was the first major reversal.
Derek did not help create the fake lease because he wanted Vanessa comfortable.
He wanted the court to believe she had cheap long-term housing.
His attorney had never seen the original fake draft.
Good.
Once the document appeared formally, Derek began distancing himself.
Yet metadata from an earlier file showed the lease template was created on his computer.
Maya warned me:
“That does not prove he forged your signature.”
Then the signature source surfaced.
Emma remembered Linda had scanned my old power-of-attorney document when Richard reorganized household records.
Why?
For a “family emergency folder.”
That folder contained copies of IDs, signatures, medical information and insurance documents for multiple family members.
I had never consented to my outdated paperwork becoming a family archive.
But years earlier, I probably shrugged when Mom said she kept important records.
Again.
Informality.
Not automatically fraud.
Then Vanessa finally admitted how the signature entered the lease.
She had asked Linda for a sample because “Ryan would sign later anyway.”
Linda emailed the scan.
Vanessa cropped the signature.
Derek placed it on the PDF.
No one signed my name by hand.
They pasted it.
Then Vanessa tried to soften it.
“We were going to tell you.”
“When?”
“Before moving.”
“After filing it?”
She started crying.
“I was scared.”
I believed that.
Fear explained urgency.
It did not explain entitlement.
Then I discovered they had done more than prepare a lease.
Derek had submitted my property address to the children’s school as their anticipated residence for the next academic year.
Vanessa had requested transportation eligibility.
A utility-transfer quote had been prepared.
A storage company had been contacted.
They were planning logistics.
Without my yes.
Then Maya found a rental-insurance inquiry.
Vanessa had asked whether renters insurance could begin on the first of the following month.
She listed herself as tenant.
Property owner contact:
Linda Mercer.
My mother.
Not me.
Why?
“Because you’re impossible to reach when you’re traveling.”
I stared at Vanessa.
“I have email.”
“You would have said no.”
There it was again.
No treated as procedural obstacle.
Then I learned something else.
Linda had told Vanessa the house was “basically family property.”
That was false.
She had contributed nothing to purchase.
Neither had Richard.
They helped me move furniture.
Dad—my biological father—was dead long before the house existed.
The down payment came from ten years of savings and a company stock payout.
Yet Linda had privately told Vanessa:
Ryan bought it because family gave him stability. He wouldn’t have that career without us.
Moral ownership.
The most dangerous category because it never appears on a deed.
I confronted her.
“You told Vanessa she had a claim on my house because you raised me?”
Linda stiffened.
“That is not what I said.”
“What did you say?”
“That families help each other.”
“Did you tell her I couldn’t have bought the house without the family?”
She paused.
“Yes.”
“Why?”
“Because it’s true.”
I felt something old rise.
Not anger about money.
Childhood.
The bracelet.
The corrections.
The years being “not real family” until responsibility appeared.
“You mean Richard raised me.”
“Yes.”
Richard flinched.
Linda continued:
“He stepped in when he didn’t have to.”
True.
Richard drove me to baseball.
Taught me how to change brake pads.
Helped with college applications.
Loved me imperfectly but genuinely.
I looked at him.
“I’m grateful.”
He nodded slowly.
Then I looked back at Linda.
“Gratitude is not a mortgage lien.”
Silence.
That sentence spread through the room.
Then Emma asked the question nobody expected.
“Mom, if family contribution creates ownership, how much of Vanessa’s things belong to Ryan?”
Linda frowned.
“What?”
“He spent years working while she lived here. He helped with Dad’s hospital bills after surgery. He paid for your roof repair. Does that mean he owns part of your house?”
Linda went quiet.
The logic stopped working once pointed in the other direction.
Then Richard said:
“There’s something you need to know.”
He looked at me, ashamed.
“About your house.”
My pulse changed.
“What?”
“Vanessa asked me six months ago whether you still had a mortgage.”
“Why?”
“I thought she was curious.”
“How much did you tell her?”
His eyes lowered.
“Enough.”
My stomach tightened.
He had disclosed my approximate mortgage balance.
My interest rate.
How much equity I likely had.
Vanessa had not simply seen spare bedrooms.
She had been studying whether my house could support them financially.
Then Richard added:
“She asked whether you’d ever take out a home-equity loan for family.”
Why would she ask that?
Vanessa did not answer.
Maya later uncovered the reason.
Derek’s failed HVAC side business owed nearly $74,000.
And months earlier, Vanessa had drafted an email to me that she never sent.
May you like
Ryan, we only need you to leverage the house temporarily.
Cliffhanger: Vanessa had not originally wanted only a place to stay—she and Derek had explored using Ryan’s home equity to rescue their failing business before the divorce ever began.
Related Stories