Chapter 3 - The Accident Was an Accident—The Money Was Not
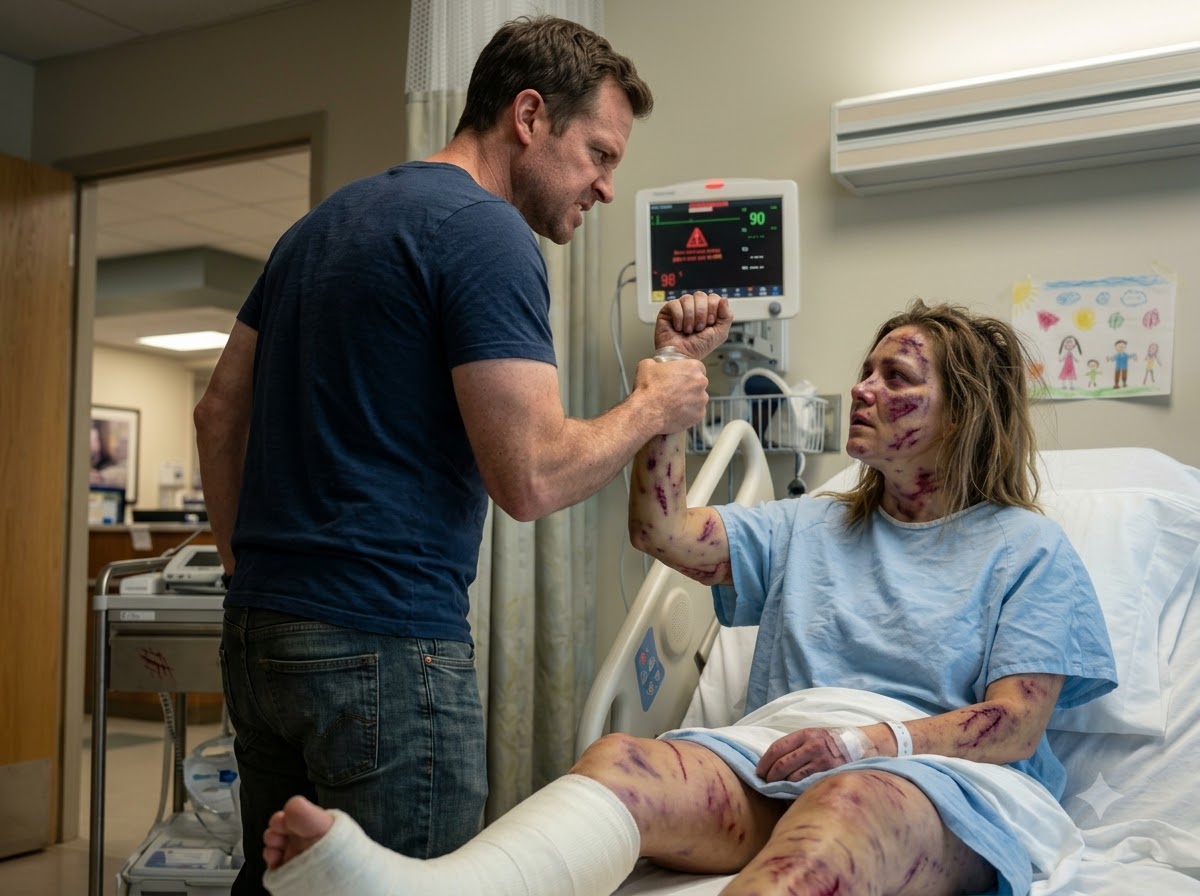
My first dangerous thought was:
Did Caleb cause the crash?
Fear likes dramatic answers.
Evidence did not support one.
The police report was clear.
Another driver ran a red light.
Traffic cameras captured it.
No vehicle tampering.
No mysterious brake failure.
No secret husband in another car.
The crash was exactly what it appeared to be:
A terrible accident.
That mattered.
I did not need to turn Caleb into a murderer to take the rest seriously.
The financial questions were enough.
The next morning I called an attorney.
Not a divorce lawyer first.
A financial attorney I knew from my accounting career: Naomi Chen.
I had trusted her years earlier with an employment-contract dispute.
Now I needed someone who understood both money and documentation.
I told her:
My husband had physically tried to remove me from hospital care.
He appeared to have interfered with rehabilitation.
I had discovered unusual home-equity transfers before the accident.
Naomi’s first instruction:
“Do not access accounts you are not authorized to access. Download only records available through your lawful logins. Preserve everything.”
Good.
Then:
“Do you want family-law counsel?”
“Yes.”
She referred me to Daniel Reeves.
Separate counsel.
Because different problems require different lawyers.
Then hospital social work helped me seek a protective order based on the assault and coercive behavior.
Not instant permanent outcome.
Temporary protections first.
Caleb could respond through court.
Emma’s arrangements would be handled carefully.
I did not ask anyone to terminate his parental rights because he grabbed my arm.
He had not been accused of hurting Emma.
But I did want communication structured and visits handled safely while the situation was assessed.
Then Naomi began with the home-equity line.
It existed.
Opened fourteen months earlier.
Jointly secured by our house.
Original amount:
$150,000.
I remembered signing something at the kitchen table.
Caleb told me it was a refinancing adjustment associated with a lower mortgage rate.
I had been rushing to Emma’s school event.
Did I sign the HELOC documents?
Electronic records showed my digital signature.
Could Caleb have forged it?
Maybe.
Could I have signed without reading?
Also possible.
I hated that.
Then verification.
The lender had emailed both of us disclosures.
To my address.
Had I seen them?
Search.
No.
They had been automatically forwarded to archive.
Who set rule?
My email account.
Created from our home computer.
Could be Caleb.
Could be me accidentally?
Unlikely.
Forensics later.
Again, no conclusion yet.
Then withdrawals.
Total used:
$121,300.
Of that:
$89,500 to C.H. Consulting.
$14,000 toward credit cards.
$9,800 cash advance.
Rest fees/other household spending.
What was C.H. Consulting?
Caleb’s side business.
He told me it was dormant.
Apparently not.
Business bank records would require discovery or voluntary production.
We did have tax returns.
C.H. Consulting reported almost no revenue.
Then why receive nearly $90,000 from home equity?
Capital contribution?
Loan?
Naomi said:
“Possible. Not necessarily illegal if he believed funds were jointly available. But concealment matters in family court, and tax treatment matters.”
Then another account appeared.
C.H. Consulting paid $36,000 to Ridgewell Ventures.
$18,000 to a crypto exchange.
$12,500 to someone named Elise Morgan.
Who was Elise?
No idea.
My stomach tightened with affair suspicion.
Naomi stopped me.
“A name is not a relationship.”
Right.
Find facts.
Then hospital investigator interviewed discharge coordinator Melissa Crane.
She remembered Caleb.
“He was persistent.”
What did he say?
That Rebecca became confused on opioids.
That she wanted home.
That rehab terrified her.
That he had healthcare authority.
Did he provide legal document?
A scanned healthcare proxy.
My pulse changed.
I had signed a healthcare proxy after Emma was born.
Caleb was named agent.
But such proxies generally activate according to their terms, often when patient lacks capacity—not simply because spouse wants control.
What did scanned document show?
There was an attached physician certification.
Not from my current attending physician.
Name:
Dr. Lewis Grant.
Who?
A physician I had never met.
Hospital credential?
No.
Private urgent-care doctor.
Certification stated:
Patient temporarily lacks capacity to make complex medical and financial decisions due post-traumatic cognitive impairment.
Financial decisions too?
Healthcare proxy would not automatically grant financial authority.
Something was wrong.
Hospital legal reviewed.
The document appeared altered.
Original proxy did not contain financial language.
The certification template was separate.
Caleb had bundled them.
Did Dr. Grant actually examine me?
No evidence.
Then Naomi searched Dr. Lewis Grant.
A real physician.
Caleb’s college friend.
My blood went cold.
Not proof of conspiracy.
We needed to know what Grant signed.
Then hospital legal contacted him.
He denied examining me.
He had written a generic statement after Caleb called asking whether severe trauma and opioids “could temporarily impair decision-making.”
He never certified me personally.
He sent a general email.
Someone converted its language into a formal-looking certification.
Dr. Grant retained the original correspondence.
That protected him, though he faced questions about why he offered medical commentary without evaluation.
Then metadata from the altered PDF.
Created on Caleb’s laptop.
The discharge interference was no misunderstanding.
He had manufactured authority.
Why?
Naomi found another clue.
Two days before my scheduled rehab transfer, C.H. Consulting applied for a business loan.
Personal guarantee required.
Applicant assets listed:
Caleb and Rebecca Hale residence — estimated equity $310,000.
My retirement account — $184,000.
My name appeared as proposed co-guarantor.
I had never agreed.
Application status:
pending documentation.
If I entered rehabilitation and began reviewing finances, perhaps I would discover it.
If I went home under Caleb’s control, maybe he believed he could obtain signatures.
Then came the transfer to Elise Morgan.
Naomi identified her through public business records.
CPA.
Forensic restructuring consultant.
Not mistress.
Maybe Caleb had hired financial help.
Then Naomi called Elise.
With my authorization to ask whether she had worked on matters involving jointly owned assets.
Elise refused details initially due client confidentiality.
Correct.
Then said:
“Rebecca, you should have your lawyer send me a formal request.”
Her tone worried me.
“Why?”
“I can’t discuss it directly.”
Then after counsel contacted her, she produced what she lawfully could.
Caleb had hired her to prepare a personal insolvency analysis.
Why?
C.H. Consulting was failing.
He owed more than $430,000 across business loans, private debt, and guarantees.
May you like
I had known none of it.
Cliffhanger: Caleb was not simply worried about hospital bills—his hidden business was collapsing under more than $430,000 in debt, and he had begun listing Rebecca’s home and retirement assets as resources to save it while she lay hospitalized.
Related Stories